- From Raw Materials to the Factory Gate: Understanding PCF, system boundaries and declared units.
- Same Molecular Formula, Different Carbon Footprints: Exploring how feedstock pathways, energy mix and accounting methodologies shape carbon footprints.
- Beyond the Factory Gate: Discovering how PCF data support supply chain transparency, Scope 3 accounting and low-carbon procurement.
The scope of carbon management is expanding beyond national and corporate emissions-reduction commitments to include emissions accounting at the supply-chain and product levels. For chemical companies operating upstream in industrial value chains, product carbon footprint data are becoming an increasingly important part of the environmental information exchanged across supply chains.
From Raw Materials to the Factory Gate: Defining the System Boundary for Product Carbon Footprints
A product carbon footprint (PCF) quantifies the greenhouse gas emissions and removals associated with a specific product system within a clearly defined life cycle boundary, in accordance with the principles of life cycle assessment (LCA). The results are expressed as carbon dioxide equivalents (CO₂e).
The calculation must be based on a clearly defined declared unit, such as 1 kg or 1 tonne of product. Results are generally expressed in kg CO₂e per declared unit. Whether the declared unit is 1 kg or 1 tonne should follow the unit specified in the product carbon footprint report.
Cradle-to-Gate is a commonly used system boundaries in the chemical industry. It covers the entire process from raw material acquisition through transportation, chemical reactions, separation and purification, up to the point at which the finished product leaves the factory. The total emissions generated throughout these stages constitute the product carbon footprint for the specified declared unit.

ISO 14067 sets out requirements for declared units, system boundaries, data quality and allocation rules, providing a framework for carbon footprints to be quantified and verified (ISO, 2018). It is important to note that PCF is an LCA-based assessment focused on climate change as a single environmental impact category. A full LCA can also evaluate other environmental dimensions, including water consumption, acidification and resource use.
Same Molecular Formula, Different Carbon Footprints
The same molecular formula does not necessarily mean the same product carbon footprint. Three key factors jointly determine the final result: feedstock pathways, energy mix and accounting methodology.

The feedstock pathway is the starting point. Assessments of petrochemical routes typically include upstream stages such as crude oil extraction, while biomass-based routes begin with the collection and use of agricultural residues.
At YINO Biologic, our production pathway starts with corncobs. Through a series of processes, including hydrolysis and catalytic hydrogenation, these non-food biomass feedstocks are processed into furan-based chemicals and downstream bio-based products, including pentanediols. For 1,5-pentanediol, the PCF assessment covers the upstream production of furfural, followed by its conversion into furfuryl alcohol and 1,5-pentanediol.
The energy mix determines the emissions intensity of the manufacturing stage. The sources of electricity and steam directly affect the carbon footprint of the manufacturing process. The accounting methodology determines how emissions are calculated and how results can be compared. Beyond the system boundary, the final result is also influenced by how environmental burdens are allocated among co-products; how primary data collected on site are combined with secondary data from industry databases; and which emission factors are selected to reflect the relevant time period and geographic region.
This shows that a carbon footprint is not a fixed label attached to a product. The same chemical can have different carbon footprint values depending on its production pathway. Only when the same accounting rules and methodologies are applied can the results be meaningfully compared.
Beyond the Factory Gate: Carbon Data Across the Supply Chain
A chemical product leaving one factory may become a raw material for another product. When calculating the carbon footprint of their own products, downstream customers need to know the greenhouse gas emissions associated with the raw materials they purchase up to the point at which those materials leave the supplier's factory gate.
Provided that data quality and accounting methodologies meet the relevant requirements, supplier-provided product-specific PCF data can offer a more detailed picture of the emissions characteristics of a particular product and its production pathway than industry-average emission factors.
To support consistent calculation and exchange of PCF data across supply chains, the chemical industry continues to develop and refine its methodologies. The Product Carbon Footprint Guideline for the Chemical Industry, published by Together for Sustainability (TfS), provides an industry reference for calculating and sharing cradle-to-gate PCF data for chemicals.

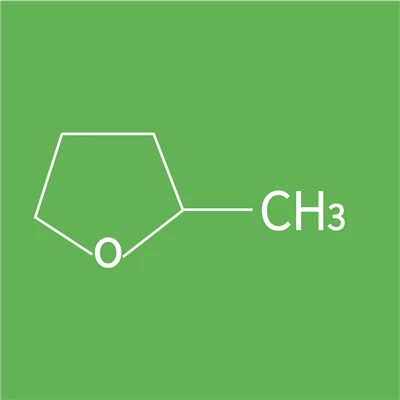
To date, YINO Biologic has completed PCF assessments for four products: 2-methyltetrahydrofuran (2-MeTHF), 1,2-pentanediol, 1,5-pentanediol and δ-valerolactone. These assessments were conducted in accordance with ISO 14067:2018 and with reference to the TfS Product Carbon Footprint Guideline, Version 3.0. All four assessments were conducted using a cradle-to-gate system boundary.
According to the company's internal calculations, the PCF values of certain products are approximately 90% lower than the corresponding industry reference values for petrochemical production routes, based on the same cradle-to-gate system boundary and declared unit. These data can provide useful support for downstream customers conducting Scope 3 accounting for purchased goods and services (Category 1) , assessing suppliers and analyzing low-carbon procurement options.
From national emissions-reduction commitments to carbon data measured per kilogram or tonne of chemicals, carbon management is becoming increasingly specific and measurable.
The value of carbon data lies in more than the figures themselves. Clearly defined system boundaries and reliable supporting data are essential if those figures are to be understood and used. As PCF accounting methodologies continue to develop, PCF data are expected to play a broader role in downstream emissions accounting and procurement assessments. Alongside molecular formulas and product specifications, a product's carbon footprint is becoming another important piece of product information.
References:
[1] International Organization for Standardization. ISO 14067:2018 Greenhouse gases - Carbon footprint of products - Requirements and guidelines for quantification[S]. 2018.
[2] World Resources Institute, World Business Council for Sustainable Development. GHG Protocol Product Life Cycle Accounting and Reporting Standard[S]. 2011.
[3] Together for Sustainability. The Product Carbon Footprint Guideline for the Chemical Industry (Version 3.0)[EB/OL]. 2024.